Gender wealth gap in Canada: INRS analysis finds women lag by about $28,000 at the median
INRS finds a median gender wealth gap in Canada of $28,000, driven by caregiving, cautious investments and notable provincial disparities and retirement risks.
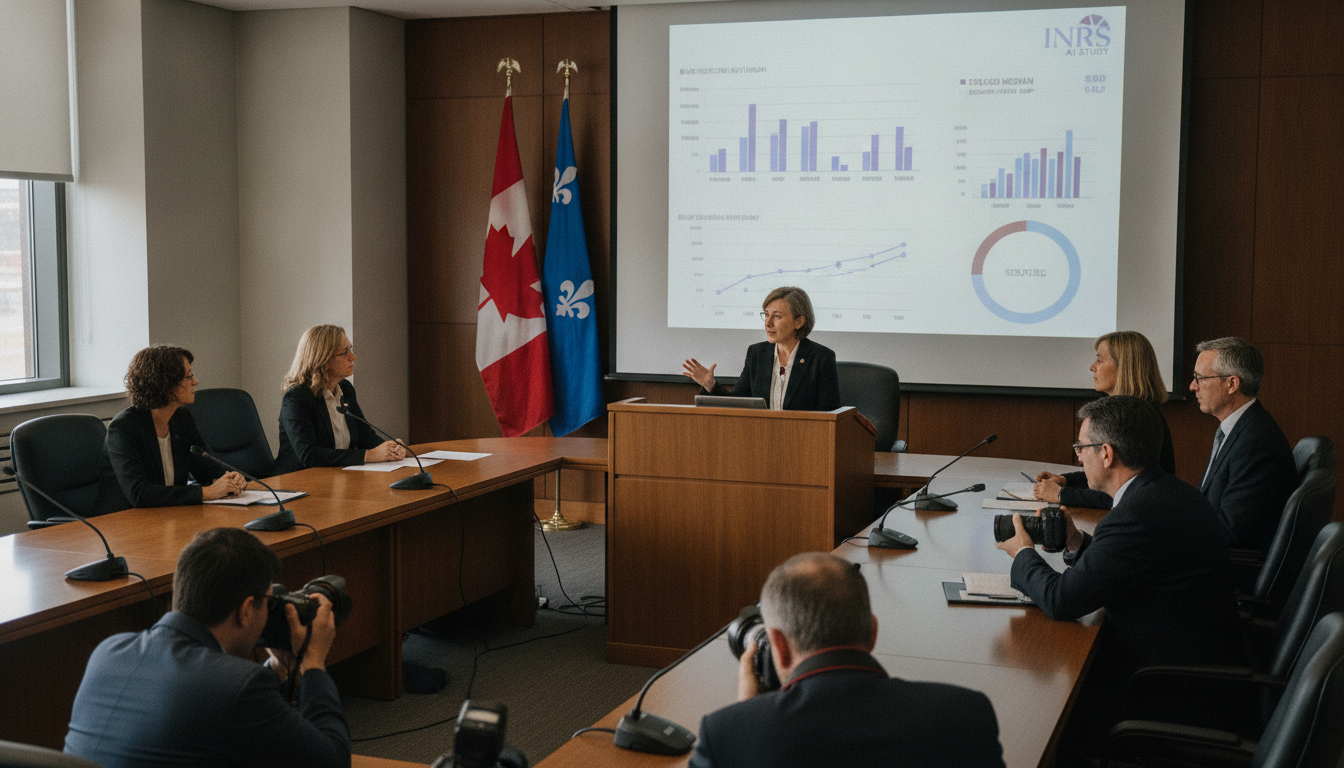
A new analysis from the Institut national de la recherche scientifique (INRS) finds the gender wealth gap in Canada is sizable, with the median Canadian woman holding roughly $28,000 less in personal net worth than the median Canadian man. The study, led by professor Maude Pugliese, used a novel statistical approach to isolate individual wealth within couples and concludes the shortfall amounts to about a 20 percent gap in median net worth. The finding builds on household-level data that traditionally obscures how assets are held within partnerships.
INRS study reveals headline figures
The INRS team translated household wealth reports into estimated individual holdings to produce national estimates of personal net worth by gender. Their work shows the median gap—measured at the center of the wealth distribution—is approximately $28,000 against women, or roughly one-fifth less than men at the median. That disparity, the researchers note, is larger than the commonly reported gender pay gap; Statistics Canada reported in 2024 that women earned about 89 cents for every dollar earned by men.
Methodology converts household data into individual estimates
Researchers trained an algorithm using data from people who live alone to predict how assets are typically distributed between partners in a household. The model was then applied to couples to estimate the portion of household assets likely owned individually by each partner versus jointly. INRS researchers contend this method offers a clearer picture of ownership and control than analyses that treat household wealth as a single pooled figure.
Caregiving and labour patterns deepen the gap
The study emphasizes that lower lifetime earnings do not fully explain the gender wealth gap in Canada. Women are more likely to take career breaks, work part time, or reduce paid hours to provide childcare and eldercare, which both reduces contributions to savings and limits opportunities for higher-paid positions. Those interruptions compound over time, affecting pension accrual, retirement savings and the ability to accumulate appreciating assets such as real estate and investment portfolios.
Different investment approaches affect long-term returns
INRS findings point to systematic differences in investment behaviour between men and women that influence wealth accumulation. On average, women in Canada tend to adopt more conservative portfolios, prioritizing capital preservation and short-term security over higher-risk, long-duration investments. This lower risk tolerance can produce smaller long-term returns, widening the net worth gap even among workers with similar lifetime earnings.
Regional disparities across provinces
The magnitude of the gender wealth gap varies significantly by province, according to the INRS research. Provinces in the Prairies, Alberta and the Atlantic region show gaps close to twice the size of those observed in Quebec, Ontario and British Columbia. The institute notes that historical trends also differ: while some provinces have seen measurable narrowing since the early 2000s, others show little change in recent years, contributing to uneven economic security for women across the country.
Implications for retirement security and policy
Researchers warn that the observed gap in individual net worth carries consequences for retirement preparedness and financial resilience in later life. Lower accumulated wealth translates into reduced pension incomes, smaller inheritances and increased vulnerability to economic shocks. The INRS team calls for richer individual-level data and targeted policy responses, such as caregiver credits, pension design reforms and measures to support investment literacy and access for women.
The INRS analysis offers new empirical footing to long-standing concerns about gendered economic inequality in Canada, suggesting that household-level statistics understate disparities in asset ownership. By estimating personal holdings within couples, the study surfaces gaps that have policy relevance for retirement systems, taxation and family supports. Continued attention to both labour-market and financial-behaviour drivers will be necessary to close the gender wealth gap in Canada and improve long-term economic security for women.
